Blog Details
- Member
- October 15, 2026
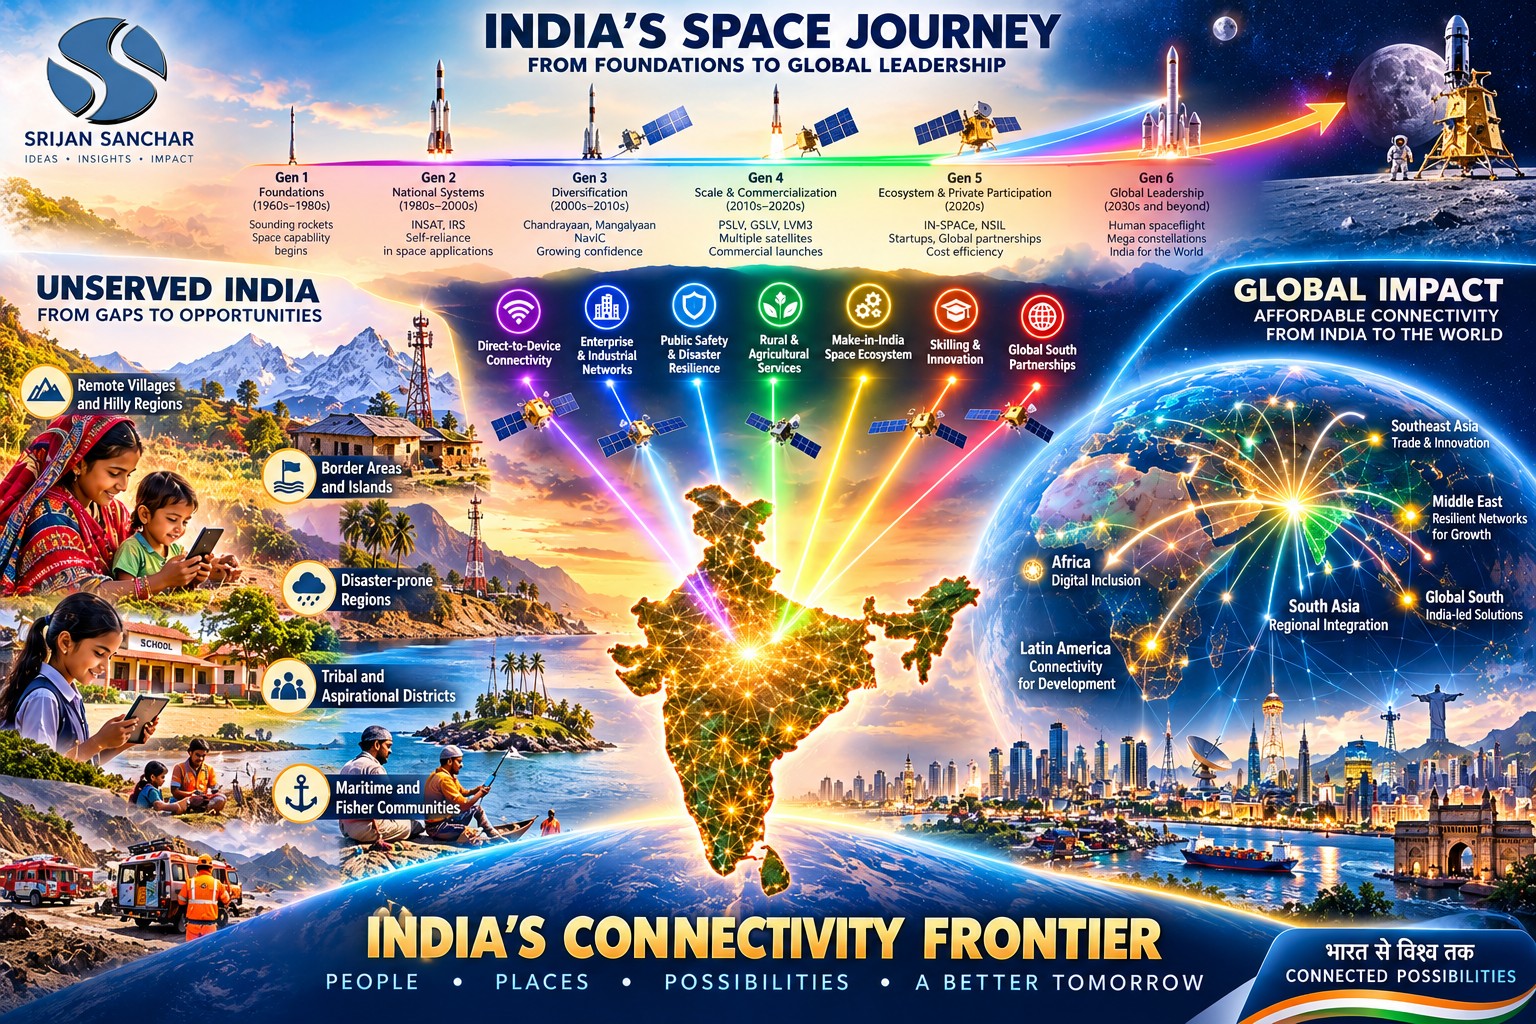
SATELLITE CONNECTIVITY INDIAN CHOICES OF PATHWAYS
SRIJAN
SANCHAR
SATELLITE
CONNECTIVITY:
INDIA’S CHOICE OF PATHWAYS
A Thought Provocation for Indian Telecom
Operators
Strategic
options for Reliance Jio, Bharti Airtel, BSNL and the wider Indian ecosystem |
October 2026
From extending coverage to reimagining
connectivity
Purpose of this thought provocation
Satellite connectivity is often framed as a
way to reach places where terrestrial networks cannot. That is an important
starting point—but it may be too narrow a destination. India could choose to
treat satellite-terrestrial convergence as a coverage extension, a new consumer
service, a mission-critical national capability, an export industry, or the
foundation of a programmable connectivity platform.
This paper reframes the strategic question:
what different futures could Indian telecom operators help create, and what
choices today would make those futures more likely? It offers a portfolio of
optional pathways rather than a single prediction or a fixed ten-year plan.
The probabilities in this document are
indicative strategic priors for discussion—not measured market probabilities,
verified forecasts, or claims of certainty. They should be revised as
regulatory decisions, technical trials, partner commitments, customer evidence
and unit economics become clearer.
Executive perspective
·
India has a potentially
distinctive combination: large telecom customer bases, an expanding private
space ecosystem, domestic engineering capability, public-sector demand and a
policy ambition to build technology at scale.
·
The strategic prize is not
simply to connect a handset to a satellite. It is to make satellite and
terrestrial connectivity behave as one dependable service—with the right
network, device, price, quality and level of sovereignty for each use case.
·
No single operator needs to own
every layer. Shared infrastructure, differentiated services and carefully
chosen domestic capabilities may produce more value than three duplicative
end-to-end stacks.
·
The most resilient strategy is
a portfolio: launch near-term services where evidence is strongest, build
options in emerging technologies, and preserve a few high-upside pathways whose
value depends on future standards, spectrum, device capabilities and economics.
·
The central choice is whether
India remains primarily a buyer and integrator of satellite capacity—or becomes
a designer, manufacturer, service orchestrator and exporter of selected parts
of the global satellite-connectivity stack.
1. A sharper strategic frame
The original roadmap usefully identifies
regulatory alignment, network convergence, domestic manufacturing, demand and
exports as connected priorities. Its main weakness is that it can read as
though the end state and sequence are already known. A decade-long roadmap is
vulnerable to changes in standards, spectrum policy, constellation economics,
handset capability, international partnerships and customer willingness to pay.
A stronger strategy separates three
questions:
|
Question |
Strategic implication |
|
What must India
secure? |
Reliable access
to satellite capacity, predictable spectrum and licensing arrangements,
interoperability, security, and resilient gateways. |
|
Where can each operator win? |
Jio may emphasize scale and consumer integration;
Airtel may emphasize enterprise and international reach; BSNL may emphasize
public-service resilience and remote-area obligations. These are hypotheses
to test, not immutable roles. |
|
What should
India own, partner for, or share? |
Choose
deliberately across devices, chipsets, antennas, network software, gateways,
constellation capacity, service orchestration, security and export channels. |
2. Optional pathways: a portfolio of possible futures
The pathways below are not mutually
exclusive. They can develop in parallel, combine, or change rank as evidence emerges.
Indicative likelihoods refer to each pathway becoming a material strategic
outcome by approximately 2030–2032, conditional on sustained execution and a
broadly enabling environment.
|
Pathway |
Indicative prior |
What it looks like |
Strategic value |
Key dependency / disconfirming signal |
|
A. Safety-net
connectivity |
70% |
Satellite SOS,
messaging and low-volume data complement terrestrial coverage, initially in
selected devices and regions. |
Visible customer
utility; relatively focused use cases; a practical route to learn. |
Device/standard
support, spectrum and service rules. Weak adoption after trials would lower
the prior. |
|
B. Enterprise and critical-infrastructure network |
65% |
Managed connectivity for energy, mining, logistics,
maritime, aviation, remote industry and business continuity. |
Higher-value contracts; service-level
differentiation; clearer value from resilience. |
Reliable performance, support model and enterprise
willingness to pay. Slow procurement or poor service economics would weaken
it. |
|
C. Public-safety
and sovereign resilience grid |
60% |
A coordinated
service for disaster response, border and island connectivity, emergency
agencies and remote public services. |
National
resilience and geographic inclusion; potential anchor demand. |
Governance,
security certification, funding and inter-agency coordination. Fragmented
procurement would slow progress. |
|
D. Hybrid mass-market mobile service |
45% |
Satellite connectivity becomes an integrated
feature of mainstream mobile plans, with terrestrial networks carrying most
traffic and satellite filling gaps. |
Large reach and brand differentiation if device and
capacity costs fall. |
Compatible handsets, capacity per user, spectrum
and sustainable pricing. Persistent high cost or limited capacity would
constrain scale. |
|
E. Indian
component and device export platform |
40% |
Indian firms
export selected antennas, RF components, terminals, software, integration and
testing capabilities. |
Domestic value
capture, jobs and supply-chain resilience. |
Competitive
performance, certification, production scale and dependable demand. Import
dependence without local learning would limit value. |
|
F. Connectivity orchestration platform |
30% |
Operators dynamically combine terrestrial,
satellite, Wi-Fi, private networks and edge services under one service layer. |
Potential platform economics and a wider role in
enterprise digital services. |
Interoperability, APIs, network intelligence and
partner access. Closed systems or poor handover quality would hold it back. |
|
G. Indigenous
constellation leadership |
20% |
Indian-led
capacity becomes a significant part of a sovereign or export-oriented
satellite network. |
Greater
strategic control and long-term ecosystem spillovers. |
Capital
intensity, launch cadence, spectrum/orbit coordination and competitive
economics. Cost or schedule overruns would lower plausibility. |
|
H. Global South managed-service champion |
35% |
Indian operators and suppliers package affordable
connectivity, devices, operations and support for selected overseas markets. |
Export revenues and international influence beyond
hardware alone. |
Country-level licensing, local partnerships,
financing and service economics. Weak local distribution or poor
affordability would stall expansion. |
3. Three strategic postures for India
|
Posture |
Core proposition |
What to do first |
What could go wrong |
|
Pragmatic
integrator |
Use available
domestic and international capacity to deliver useful services quickly. |
Run focused
trials; secure partner options; standardize service interfaces; measure real
demand and cost per covered user. |
India gains
users but captures limited technology value and remains dependent on external
capacity. |
|
Selective capability builder |
Integrate globally where sensible while building
chosen Indian strengths in devices, RF, antennas, software, gateways,
security and testing. |
Identify a small number of exportable components
and service capabilities; link procurement to testing, learning and
certification. |
Too many localization targets dilute capital and
delay competitive products. |
|
Platform and
ecosystem architect |
Make India a
place where multiple networks, device makers, public agencies and service
providers can combine capabilities. |
Develop
interoperable service orchestration, common test environments, shared
infrastructure rules and reference deployments. |
Coordination
overhead, unclear accountability and premature platform building before
demand is proven. |
Thought provocation: India does not have to
choose one posture for every layer. It can be a pragmatic integrator in
constellation capacity, a selective capability builder in antennas and network
software, and an ecosystem architect in interoperability and public-safety use
cases.
4. Operator pathways: distinct roles, shared foundations
Reliance Jio — make hybrid connectivity feel ordinary
Potential lead: integrate satellite
connectivity into a broad digital and mobile experience, starting with
high-clarity use cases and moving toward wider device support only when
economics and performance justify it.
·
Near-term option: controlled
SOS, messaging and remote-coverage pilots with transparent limitations and
customer education.
·
Build option: test compatible
devices, chipset/antenna partners, network-core integration and seamless
service management.
·
Scale option: low-cost add-on
or bundled plans only after measuring satellite capacity, device premiums,
support costs and usage patterns.
·
Watchpoint: avoid promising
ubiquitous broadband or seamless voice before capacity, standards and device performance
support the claim.
Bharti Airtel — turn reliability into an enterprise
product
Potential lead: package satellite and
terrestrial connectivity for enterprises that value continuity, geographic
reach, managed service and support more than the lowest headline price.
·
Near-term option:
sector-specific deployments in remote industrial sites, logistics, maritime,
energy and business continuity.
·
Build option: dual-mode
terminals, managed network operations, cross-border service partnerships and
clear service-level tiers.
·
Scale option: export a
repeatable managed-service offer into selected markets where Airtel has strong
enterprise relationships or credible local partners.
·
Watchpoint: differentiate on
measurable service outcomes; avoid assuming that satellite capacity alone
creates a defensible premium.
BSNL — make resilience a measurable public capability
Potential lead: support public safety,
remote-area connectivity and continuity for government and essential services,
with an explicit service and governance model.
·
Near-term option: map priority
sites and scenarios—disaster response, islands, remote terrain and critical
public infrastructure—and test end-to-end response.
·
Build option: secure terminals,
resilient gateways, operational drills, trained field support and agreements
with relevant agencies and capacity providers.
·
Scale option: procure against
coverage, readiness, response time, availability and lifecycle cost rather than
equipment counts alone.
·
Watchpoint: a
sovereign-resilience ambition needs a funded operating model, clear command
responsibilities and realistic capacity assumptions.
Shared foundations that may be more valuable than
duplication
|
Shared foundation |
Possible arrangement |
Safeguard |
|
Test and
validation environment |
Common trials
for devices, handover, emergency operation, security and interoperability. |
Keep test
results transparent and preserve competition in retail offers. |
|
Remote gateways and selected infrastructure |
Share where it reduces duplicated cost and improves
resilience. |
Define access, redundancy, cybersecurity, ownership
and outage responsibilities. |
|
Domestic
supplier development |
Jointly
articulate technical requirements and give suppliers credible test
opportunities. |
Avoid a
single-source ecosystem; require performance and lifecycle-cost evidence. |
|
Public-safety readiness |
Common protocols, exercises and minimum service
expectations across relevant operators and agencies. |
Make accountability, escalation and data access
explicit. |
|
Interoperability
and service APIs |
Agree interfaces
that let services work across devices and networks where technically and
commercially feasible. |
Do not confuse
interoperability with a requirement to use one vendor or one architecture. |
5. A staged decision roadmap
The dates below are decision windows, not
promises of commercial readiness. Each phase should end with an evidence-based
go, adapt, partner or stop decision.
|
Window |
Priority moves |
Evidence required to proceed |
Decision gate |
|
0–18 months |
Clarify
regulatory and spectrum pathways; choose a small number of use cases; conduct
field trials; establish baseline economics; map partner and supplier options. |
Measured
coverage and availability; device compatibility; real-world performance;
customer and agency feedback; security and compliance review. |
Proceed only
where a defined user need and credible delivery model exist. |
|
18–36 months |
Commercialize selected services; expand enterprise
and public-safety deployments; test domestic components; develop repeatable operating
playbooks. |
Paid usage or funded commitments; support cost;
unit economics; reliability across seasons and geography; supplier quality. |
Scale proven offers; redesign weak ones; keep
emerging options alive through partnerships. |
|
3–5 years |
Expand
compatible devices and sectors; build exportable service packages; strengthen
local component and software capability. |
Repeat
customers; certification; partner performance; competitive cost; evidence of
local value capture. |
Concentrate
investment on the few capabilities where India is demonstrably competitive. |
|
5–10 years |
Consider deeper platform orchestration, larger
domestic capacity commitments and wider exports where evidence supports them. |
Sustained demand, financing, technology maturity, regulatory
clarity and resilient supply chains. |
Commit major capital only when the strategic case
survives downside scenarios. |
6. Signals that should change the pathway ranking
|
Signal to monitor |
If it improves |
If it disappoints |
|
Spectrum,
licensing and international coordination |
Accelerate
trials and commercial planning for affected bands and use cases. |
Shift effort to
services and bands with clearer authorization; avoid sunk-cost escalation. |
|
Compatible handset and chipset availability |
Raise the plausibility of consumer-facing services
and broader device integration. |
Concentrate on dedicated terminals, enterprise and
emergency use cases. |
|
Cost per usable
connection and capacity per user |
Broaden the
addressable market and test lower-price bundles. |
Keep satellite
as a targeted complement rather than promising universal mass-market service. |
|
Field reliability and handover performance |
Move from pilots to service-level commitments in
proven contexts. |
Narrow the geography, device set or service promise;
publish limitations honestly. |
|
Domestic
supplier quality and export certification |
Increase local
sourcing and export options selectively. |
Use global
components where necessary while investing in specific capability gaps. |
|
Anchor contracts and repeat usage |
Support capacity commitments and repeatable
deployment models. |
Delay large capital commitments; revisit the
problem definition and value proposition. |
7. Risks that deserve explicit treatment
|
Risk |
Why it matters |
Practical response |
|
Technology and
standards uncertainty |
Device support
and network interoperability may evolve unevenly. |
Design trials
around multiple plausible standards and avoid tying the entire plan to one
assumed architecture. |
|
Capacity and service-quality gap |
A satellite link is not automatically equivalent to
terrestrial broadband or voice. |
Define service by use case; measure latency,
throughput, availability, congestion and handover in the field. |
|
Capital and
utilization risk |
Constellations,
terminals and network integration can require large commitments before demand
is proven. |
Use staged
investment, shared assets where appropriate, anchor customers and explicit
exit gates. |
|
Regulatory and coordination risk |
Spectrum, licensing, security and cross-border
permissions can shape the viable business model. |
Maintain a joint policy-and-industry dialogue while
preserving clear legal accountability for each operator. |
|
Over-localization
risk |
Domestic
sourcing goals can increase cost or delay deployment if capability is not yet
competitive. |
Localize
selectively against quality, lifecycle cost, learning value and export
potential. |
|
Sovereignty versus interoperability |
National control and international reach can pull
in different directions. |
Classify requirements by service criticality;
define where sovereign control is essential and where partnerships are
acceptable. |
|
Forecast
overconfidence |
Long-range plans
can turn assumptions into commitments. |
Use scenario
triggers, quarterly evidence reviews and reversible decisions wherever
possible. |
8. A practical scorecard for choosing what to pursue
Evaluate each candidate pathway against the
same questions. Scores should be assigned by the responsible team using trial
results and partner evidence; this document does not invent scores where
evidence is absent.
|
Criterion |
Question for decision-makers |
Suggested evidence |
|
Strategic value |
Does this solve
an important problem for India or a defined customer? |
User interviews,
agency requirements, sector demand and consequences of service failure. |
|
Feasibility |
Can the service be delivered with available
standards, devices, capacity and permissions? |
Field trials, compatibility tests, regulatory
advice and engineering validation. |
|
Economics |
Can the service sustain
its price, cost to serve and support obligations? |
Cost per active
user/site, utilization, device cost, support costs and willingness to pay. |
|
Indian value capture |
Does India build reusable capability, IP, supplier
learning or exportable services? |
Domestic supplier participation, certification,
engineering ownership and export pipeline. |
|
Resilience and
security |
Does it improve
continuity without creating unacceptable vulnerabilities? |
Threat
assessment, redundancy, incident drills, recovery time and data governance. |
|
Option value |
Does a modest investment preserve access to a
high-upside future? |
Partner options, modular architecture, standards
participation and low-cost experiments. |
9. Decisions to put on the table now
·
Choose a limited set of first-wave
use cases where satellite connectivity has a clear advantage—not merely a
novelty factor.
·
Agree which capabilities should
be shared, competitively differentiated, sourced internationally or developed
in India.
·
Create a common evidence agenda
for trials: performance, reliability, user value, lifecycle economics, security
and operational readiness.
·
Set explicit scale / adapt /
stop gates before committing to large capital expenditure or nationwide
promises.
·
Treat public safety as an
end-to-end operating capability, including people, procedures, terminals,
support and drills—not just network coverage.
·
Build a focused domestic
capability portfolio around demonstrable technical and export opportunities
rather than a blanket localization target.
·
Revisit the pathway ranking at
regular intervals as standards, regulation, costs and customer evidence change.
Closing thought
The
question is not whether satellites will be part of India’s connectivity future.
The question is what role India chooses to play in shaping that future.
A coverage extension is a valid beginning.
It need not be the final ambition. India can combine pragmatic partnerships
with selective domestic capability-building and, where evidence warrants,
become an architect of interoperable connectivity services. The winning pathway
will not be the most dramatic forecast; it will be the one that converts a
clear purpose into tested behaviour, learns from evidence and evolves before
its assumptions become liabilities.
Basis and interpretation
Company-specific roles and all pathway
probabilities are hypotheses for discussion. They are not independently
verified statements about current commercial readiness, confirmed operator
plans or measured likelihoods.
Before using this paper for investment,
regulatory or public commitments, validate all time-sensitive claims, policy
status, technical readiness, partner arrangements and financial assumptions
against current primary sources and operator evidence.